Experian®

Screenshots
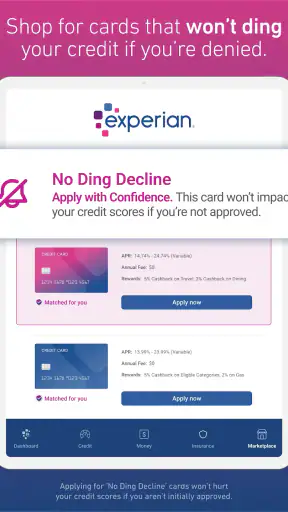
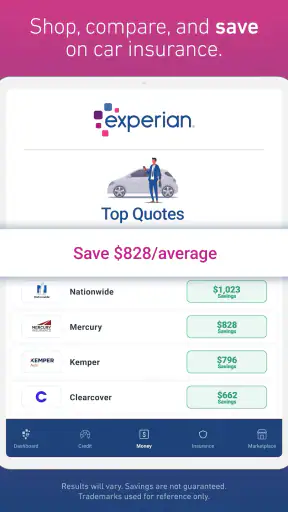
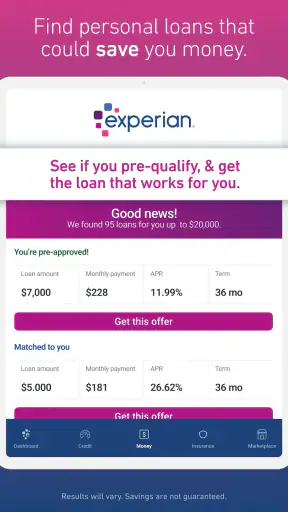
Details
- Rating
- 200.34K reviews
- Version
- 4.2.13
- Developer
- Experian
Analysis by Norviv
I like Experian best as a credit-checking companion, not as a complete personal finance manager. Its main value is helping me see what is happening on my credit file and giving me a place to investigate changes. That makes it useful for people who want to be more deliberate about borrowing, but less suited to anyone expecting a full budgeting app that tracks every bill and spending category.
Made by Experian, a company focused on credit information, this free finance app has a 4.7 average from around 699,000 ratings and more than 10 million installs. It is rated for everyone, and its current version is 4.2.13. Those figures suggest it has broad appeal, but I would still judge it by whether its credit tools fit your habits and goals.
What I would use it for day to day
The strongest reason to keep Experian on my phone is having a regular point of reference. Instead of waiting until I apply for a loan or card to think about credit, I can check in, review what is reported, and notice whether something looks unfamiliar. The score itself is only a snapshot; the more useful habit is checking the underlying account information and understanding what may be influencing it.
For example, if I were planning to apply for a car loan, I would use the app beforehand to review my report and look for errors or accounts I had forgotten about. I would treat that as preparation, not as a promise of approval or a substitute for checking the lender’s own requirements. A credit score can help me orient myself, but lenders may assess applications using their own criteria.
Small decisions that make the app more useful
One practical approach is to check the report when something changes in real life: after opening or closing an account, paying down a balance, or noticing a credit-related notification. That gives me a reason to inspect the details rather than repeatedly refreshing a number that may not move immediately. If a change seems wrong, I would first compare it with my own statements and records before deciding what action to take.
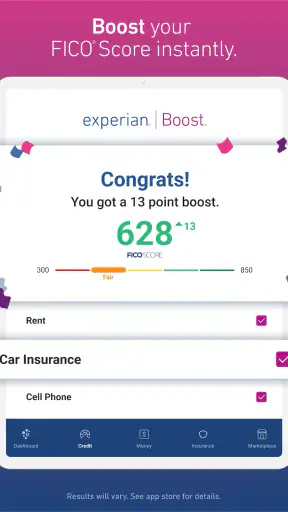
Experian Boost is worth approaching with realistic expectations. Linking eligible utility or telecom payments may help some people, but it is not a universal shortcut and a score change is not guaranteed. I would review what information I am connecting and consider whether the possible benefit is worth sharing it. If I try it, I would note my score beforehand and judge the result over time instead of expecting an instant leap.
Where credit monitoring differs from budgeting
Compared with a typical budgeting app, Experian is aimed at credit history and credit awareness rather than organizing day-to-day spending. A budget tool is usually the better choice if I want to categorize purchases, plan a monthly cash flow, or see how much I have left for groceries. Experian makes more sense when the question is whether my credit profile looks healthy and whether a report change deserves attention.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
It can also complement, rather than replace, checking information through a bank, card issuer, or lender. Those services are closer to the accounts and transactions they manage; Experian gives a credit-focused view. I would avoid treating any one app as the final authority when applying for credit or resolving a reporting issue. Comparing the relevant records across sources is a sensible way to catch mismatches.
Who should choose it—and who may not need it
I would recommend Experian to someone building credit for the first time, preparing for a major application, or simply trying to understand how account history and credit use fit together. Its score breakdown and prompts can make an unfamiliar subject easier to approach. People who already check their reports through other trusted services may find it redundant unless they specifically want Experian’s tools or alerts.
It is also not the right fit for someone who wants personalized financial advice from a human adviser, a complete household budget, or a guarantee that a score will rise. The app can point out information and offer guidance, but I still need to decide what applies to my circumstances. I would use its suggestions as prompts to investigate, not as instructions to make a financial move without considering the wider costs.
Have you ever found yourself wondering just how reliable your credit score is? Enter Experian, the app that promises to make managing your credit a breeze. I recently decided to give it a whirl, and let me tell you, it’s like having a personal finance advisor right in your pocket.
Getting Started with Experian
First off, setting up Experian is as easy as pie. You just download it from your app store, create an account, and within a few taps, you’re in. The interface is clean and user-friendly, which is a big win for those of us who aren’t exactly tech-savvy. The app quickly pulls up your credit score, and you immediately get a snapshot of your financial health. It’s like getting a physical exam, but for your wallet.
Your Credit at a Glance
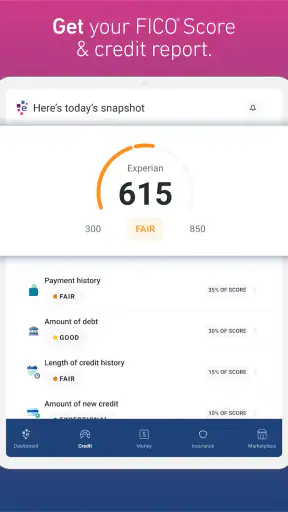
The first thing that caught my eye was the dashboard. It’s neat and tidy, with your credit score displayed prominently. You also get a quick overview of your credit accounts, including any loans or credit cards. It’s a relief to have all this info in one place without having to dig through endless paperwork. Plus, Experian updates your score regularly, so you’re always in the loop.
What really stood out to me was the Experian Boost feature. This nifty tool allows you to potentially increase your score by linking your utility and telecom payments. It’s like getting extra credit for being a responsible adult. I tried it out, and while it didn’t make a huge difference immediately, every little bit helps, right?
Insights and Alerts
One of the most useful features of Experian is its insights and alerts. The app doesn’t just show you numbers; it actually helps you understand them. You get personalized tips on how to improve your score, which is a nice touch. It’s like having a financial advisor whispering in your ear.
And let’s talk about alerts. I once got a notification about a hard inquiry on my report that I didn’t recognize. Thanks to Experian, I was able to catch it early and take action. It’s these little things that make the app invaluable. It’s like having a watchdog on your side, making sure your credit stays safe and sound.
Why Experian Stands Out
I’ve tried a few other credit monitoring apps, but Experian offers a level of detail and reliability that’s hard to beat. The credit report section is thorough, breaking down your score into factors like payment history, credit utilization, and more. It’s like getting a full report card for your financial behavior.
Plus, the fact that it’s free is just the cherry on top. There are premium features, of course, but the basic version gives you more than enough to work with. It’s like having a toolbox full of gadgets you didn’t know you needed.
Wrapping It Up
So, is Experian worth your time? Absolutely. Whether you’re a credit newbie or a seasoned pro, this app offers something for everyone. It’s intuitive, informative, and frankly, a bit of a lifesaver in the world of personal finance. You won’t become a credit expert overnight, but with Experian, you’ll certainly feel more in control. And in today’s world, that’s a pretty big deal.
All in all, if you’re looking to keep tabs on your credit score without the hassle, give Experian a shot. You might just find it’s the financial buddy you never knew you needed.
That helpfulness has a boundary: a clean dashboard can make the score feel more definitive than it is. I would read it as a guide to the information Experian holds, not a universal verdict on my finances. A score is one part of a lender’s decision, and a change in the app does not necessarily mean a lender will make the same assessment. Keeping that distinction in mind prevents a useful monitoring tool from turning into a source of unnecessary confidence or worry.
How I would handle an unexpected alert
If a notification flags an inquiry or account I do not recognize, I would avoid tapping through in a panic. First, I would check the report entry and compare its details with recent applications and correspondence. A hard inquiry can be unfamiliar because a lender or dealership used a different name, so I would verify before assuming fraud. If it still appears unauthorized, I would follow the relevant reporting and dispute steps rather than relying on the alert alone to resolve it.
This is where notifications are most valuable: they shorten the time between a possible issue appearing and my noticing it. They do not, by themselves, prove what happened or fix an error. I would also keep my own records of applications and account changes, so I have something concrete to compare against the report when a notice arrives.
Privacy and account setup deserve a pause
Because the app deals with sensitive financial information, I would take the account setup seriously even if the screens feel simple. I would use a strong, unique password and make sure I understand the identity-checking prompts before entering details. Convenience is useful, but credit monitoring works only if I am comfortable with the information I am putting into the service and with keeping the account secure.
The same care applies to Boost. I would consider whether the bills I want to connect are in my name and whether the payment history is likely to help my situation before linking anything. If the potential effect is modest, or I would rather keep those records separate, skipping the feature is a reasonable choice. The app can still be useful for checking credit information without treating every optional tool as essential.
Making the score breakdown actionable
When a factor such as payment history or credit utilization appears in the report, I would turn it into a question rather than a quick prescription. For utilization, for instance, I would review balances and limits on my own statements and consider whether paying down a balance is affordable. I would not take on a new account simply because an app suggests that more available credit might change a score; the costs and my ability to manage another bill matter more than chasing a number.
For a first-time credit user, the breakdown can be a useful learning aid because it connects abstract score movement to familiar behaviors. For someone with a long history, the same guidance may feel broad or repetitive. In either case, its value is greatest when I use it to identify a specific item to verify or a habit to review, not when I treat every tip as tailored financial planning.
A sensible routine, without score-watching
I would build a light routine around the app: check the report periodically, pay closer attention after a meaningful account change, and investigate alerts that do not match my records. Constantly opening the app to see whether the score has shifted is unlikely to teach me much and can make small fluctuations feel more important than they are. A calm review of the underlying details is more useful than reacting to each movement.
That routine also makes it easier to decide when Experian is no longer adding much. If I already have a reliable way to monitor the reports I care about and do not use its alerts or score explanations, keeping another finance app may add clutter rather than insight. On the other hand, a person who wants one recognizable place to start learning about credit may appreciate having the report, explanations, and notifications together.
My recommendation in context
Overall, I see Experian as a practical entry point for credit awareness, with the strongest case for people who will actually inspect report details and follow up on unfamiliar changes. Its everyday usefulness comes from making those checks less intimidating, not from replacing a lender, a budget, or careful judgment. I would install it if credit visibility is a current goal; I would skip it if I only want help tracking household spending or already have a monitoring routine that works.
The app has been available since May 12, 2016, and its minimum operating-system requirement is version 8.0. That makes it worth checking compatibility before installing on an older device. If your phone supports it and you are comfortable managing credit information in an app, the free starting point is appealing. My verdict is positive, with one clear condition: use Experian to become better informed, not to let a single score make financial decisions for you.
Frequently Asked Questions
01What is the main purpose of the Experian app?
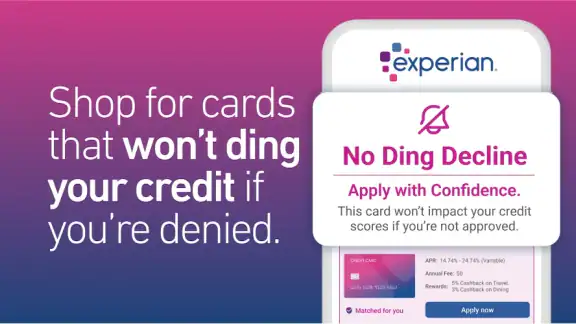
The Experian app is designed to help users monitor their credit scores and reports. It provides real-time alerts about changes in your credit file, offers personalized insights to improve your credit health, and gives access to your FICO® Score. This makes it a valuable tool for anyone looking to manage their credit effectively.
02Is the Experian app free to use?
The Experian app offers both free and paid features. Users can access their Experian credit report and FICO® Score for free. However, there are premium services, such as identity theft protection and advanced credit monitoring, available through a monthly subscription. Evaluating these options can help you decide what fits your needs best.
03How secure is my personal information on the Experian app?
Experian employs advanced security measures to safeguard user data. Encryption and two-factor authentication are used to protect your personal information. Regular security audits and compliance with financial industry standards ensure that your data remains secure while using the app.
04Can I dispute errors on my credit report through the Experian app?
Yes, the Experian app allows users to dispute inaccuracies directly from the app. If you notice any errors on your credit report, you can easily file a dispute. The app provides a streamlined process to ensure your disputes are handled efficiently, helping to maintain the accuracy of your credit information.
05Does the Experian app offer financial advice or credit improvement tips?
The Experian app provides personalized insights and recommendations to help improve your credit score. It analyzes your credit behavior and suggests actionable steps you can take. Whether it's paying down debt or managing credit utilization, the app guides you towards better financial health.


